Businesses fixed. Deals made.

Lorand Minyo established Minyo & Co to advise owners, boards and investors on businesses in difficulty and on the partnerships, transactions and investments that their plans require. He brings twenty-six years of experience building and running companies in regulated markets, technology, healthcare and defence, and accepts only a limited number of mandates.

The practice

Our work falls into two parts, which are frequently stages of a single engagement.

Businesses under strain

We are asked to act when an operation is failing, when a regulator has begun to take an interest, when a platform can no longer carry the business built upon it, or when losses have outrun any explanation of them. In such circumstances we assume responsibility for the situation, restore stability and remain engaged until the business is secure.

  • Turnaround and restructuring
  • Regulatory and supervisory pressure
  • Interim executive leadership
  • Operations that will not scale
  • Compliance, licensing and payment relationships
  • Preparing a business for sale after a period of difficulty

Transactions and partnerships

We also act for clients who need to secure a manufacturing partner, enter a new market, raise capital, acquire a competitor or sell a business, often in jurisdictions where they have no relationships of their own. We identify the right counterparty, make the introduction and advise on the arrangement through to signature.

  • Counterparty search and introduction
  • Manufacturing, supply and offtake partners
  • Market entry, licensing and distribution
  • Joint ventures and strategic partnerships
  • Equity and debt capital
  • Sale, acquisition and merger

The principal

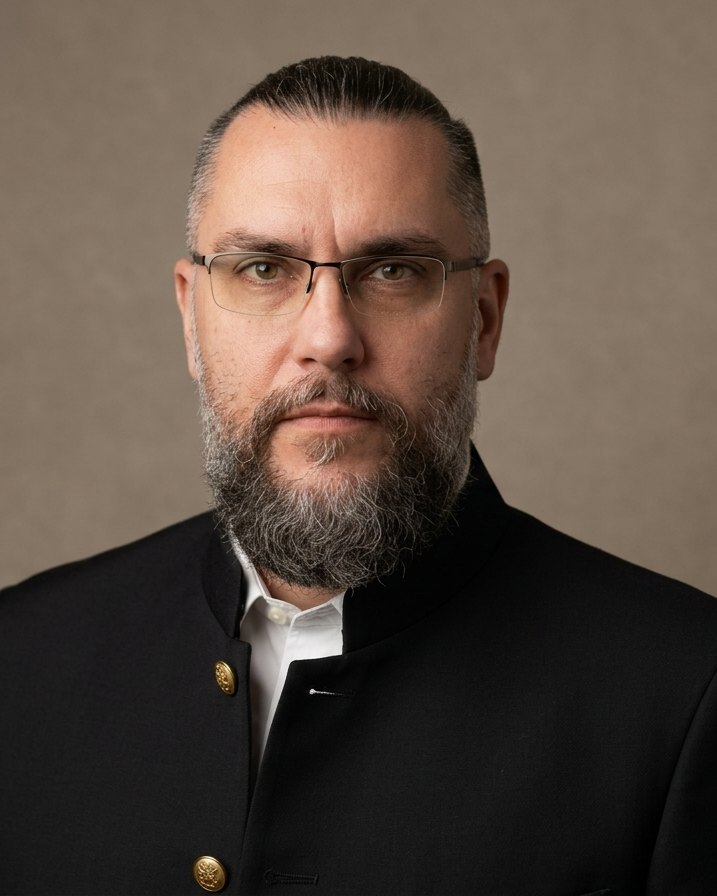
Lorand Minyo

Lorand Minyo

Founder

Lorand Minyo began his career in 2000 and has since held senior commercial and operating roles across e-commerce, regulated gaming, financial technology, healthcare, renewable energy, robotics and defence.

Having started in go-to-market, he has remained close to the commercial side of the businesses he has led, negotiating the partnerships, distribution arrangements and payment relationships on which they depended. As chief operating officer and then chief executive of a regulated technology platform, he built the operational and compliance infrastructure that carried the business across several jurisdictions and past $400m in annual recurring revenue, led a nine-figure operation through a turnaround under regulatory pressure, and completed a clean exit. Earlier he co-founded a cosmetics manufacturer, a video-recognition product and a healthcare company.

Born and raised in Transylvania, he works internationally and speaks English, Romanian, Hungarian and Italian.

Record

26 years
In business since 2000, across technology, regulated markets, healthcare and defence
$400m+
Annual recurring revenue of businesses whose operations he has run, across multiple jurisdictions
Clean exit
A business steadied while under supervisory scrutiny and taken through to a completed sale
350%
Sales growth delivered, with net promoter score moved from 4 to 9
Expertise

Most engagements draw on more than one of these disciplines, not least because a business is so often put right in order to be sold.

Operations under pressure

Turnaround, restructuring and interim leadership: assuming responsibility for an operation in difficulty, establishing the causes, and managing it until it can once again stand on its own. The work extends through the period in which cash, staff and customers are all in motion at once.

Regulated markets

Licensing, compliance frameworks, multi-jurisdiction operations and payment provider relationships are where regulated businesses most often come to grief. Lorand Minyo has run a business subject to all four and answered to its supervisors directly, so the judgement offered here comes from having carried the obligation himself.

Partnerships and market entry

Finding and securing the counterparties a business needs in order to grow, whether a manufacturing or supply partner, an offtaker, a licensee or distributor, or the person inside an organisation with the authority to decide, and very often across a border the client has not crossed before. This can be the whole of an engagement, and is often how a longer relationship begins.

Sale, acquisition and merger

Advice on either side of a transaction: preparing the business for market, identifying and qualifying counterparties, conducting the process, and negotiating terms until the deal closes.

Capital and funding

Raising equity and debt, from preparing the business and its materials to shaping the approach and managing the sequence in which investors and lenders are contacted. Where a jurisdiction requires an authorised intermediary to arrange or place capital, one is appointed to do so.

Technology and product judgement

An honest assessment of what a technology business has built: the state of the platform, what it costs to operate, the credibility of the roadmap, and whether the engineering can support the commercial plan, which is as useful to a buyer in diligence as it is to an owner preparing to go to market.

Sectors

These are the sectors in which we have operated directly. We take instructions outside them as well, and where an engagement calls for technical expertise beyond our own, we bring in specialists and tell the client who they are.

  • Regulated gaming and licensed platforms
  • Financial technology and payments
  • Technology and software
  • Applied artificial intelligence
  • Healthcare and life sciences
  • Defence and autonomous systems
  • Robotics and hardware
  • E-commerce and consumer
  • Energy and renewables
  • Biotechnology
  • Manufacturing
  • Professional services

Perspectives

Occasional notes on regulated markets, operations under strain, and what changes hands when a business is sold.

Regulated markets

What supervision actually tests

When a regulator arrives, what it sets out to establish is whether the operation can evidence its own behaviour: who approved what, on what basis, and how quickly that can be shown. Platforms tend to fail supervision on record-keeping and escalation well before any question of policy arises, which is why preparing for it is largely a matter of making an organisation legible to itself.

Operations

The order you fix things in

A business in trouble presents every problem at once, and the instinct is to turn to whichever seems most frightening. The order that works is less dramatic: cash first, because it buys the time in which everything else can be done; then the operation, since a business that cannot deliver will not be rescued by a narrative; and the story last, once the first two have made it true, which is precisely the sequence that failed turnarounds so often reverse.

Transactions

Why buyers discount a regulated business

A company built inside a licensing regime usually sells at a discount, which its owners tend to resent and which buyers justify by the risk that the licence, the payment relationships or the compliance record will not survive a change of control. Most of that discount can be recovered, but only through work done in the eighteen months before a sale process begins.

Working with us

The first conversation

An initial conversation carries no fee and no obligation on either side. We use it to understand what you are trying to achieve, to say whether we are the right firm for it, and to give you a view on what the work would involve.

Terms of engagement

Scope, duration, fees and expenses are agreed in writing before work begins. Fee structures vary with the instruction and commonly combine a retainer with a fee payable on completion.

Confidentiality

We treat an approach as confidential from the first contact, do not publish our engagements or name clients and counterparties to third parties, and will sign a non-disclosure agreement at whatever point you would like one.

Your other advisers

Most engagements run alongside a client's existing lawyers, accountants and bankers. We coordinate with them, share what they need, and leave their relationships intact.

Through to completion

We stay with an engagement after heads of terms are agreed and through diligence, documentation and closing, the period in which a substantial share of the work in any transaction falls.

Mandates

At any given time we hold mandates that range from the sale or purchase of a company to the search for the counterparties on which a business depends: a manufacturing partner in East Asia for a European engineering firm, an offtake buyer in the Gulf for a gold producer, a distributor or licensee in a country the client has never entered, or the investor best suited to a particular asset. Much of this work is carried out across borders, and very few of these engagements are ever advertised.

If you are looking for a partner, a supplier, a buyer, an investor or a way into a new market, or you hold a business, an asset or a capability that others may need, we would be glad to hear what you have in mind. Where one of our mandates corresponds to it, we will tell you so, and no introduction is made without the consent of both parties.

Contact

Where we work

Minyo & Co acts for clients internationally, alongside partners and associates in the centres below and in more than thirty further countries.

Brazil

São Paulo

China

Beijing

Egypt

Cairo

Israel

Tel Aviv

Japan

Tokyo

Saudi Arabia

Riyadh

Singapore

Singapore

South Korea

Seoul

Switzerland

Zurich

United Arab Emirates

Dubai

United Kingdom

London

United States

New York

View all locations

Europe

Amsterdam Athens Berlin Budapest Istanbul London Nicosia Paris Rome Warsaw Zurich

Middle East and Africa

Accra Amman Cairo Doha Dubai Johannesburg Lagos Muscat Nairobi Rabat Riyadh Tel Aviv Tunis

Asia-Pacific

Astana Bangkok Beijing Hanoi Jakarta Kuala Lumpur Manila New Delhi Seoul Singapore Sydney Tokyo

Americas

Bogotá Buenos Aires Havana Mexico City New York Panama City Santiago São Paulo Toronto